
London New Build Market Statistics: Prices, Boroughs & Supply Report
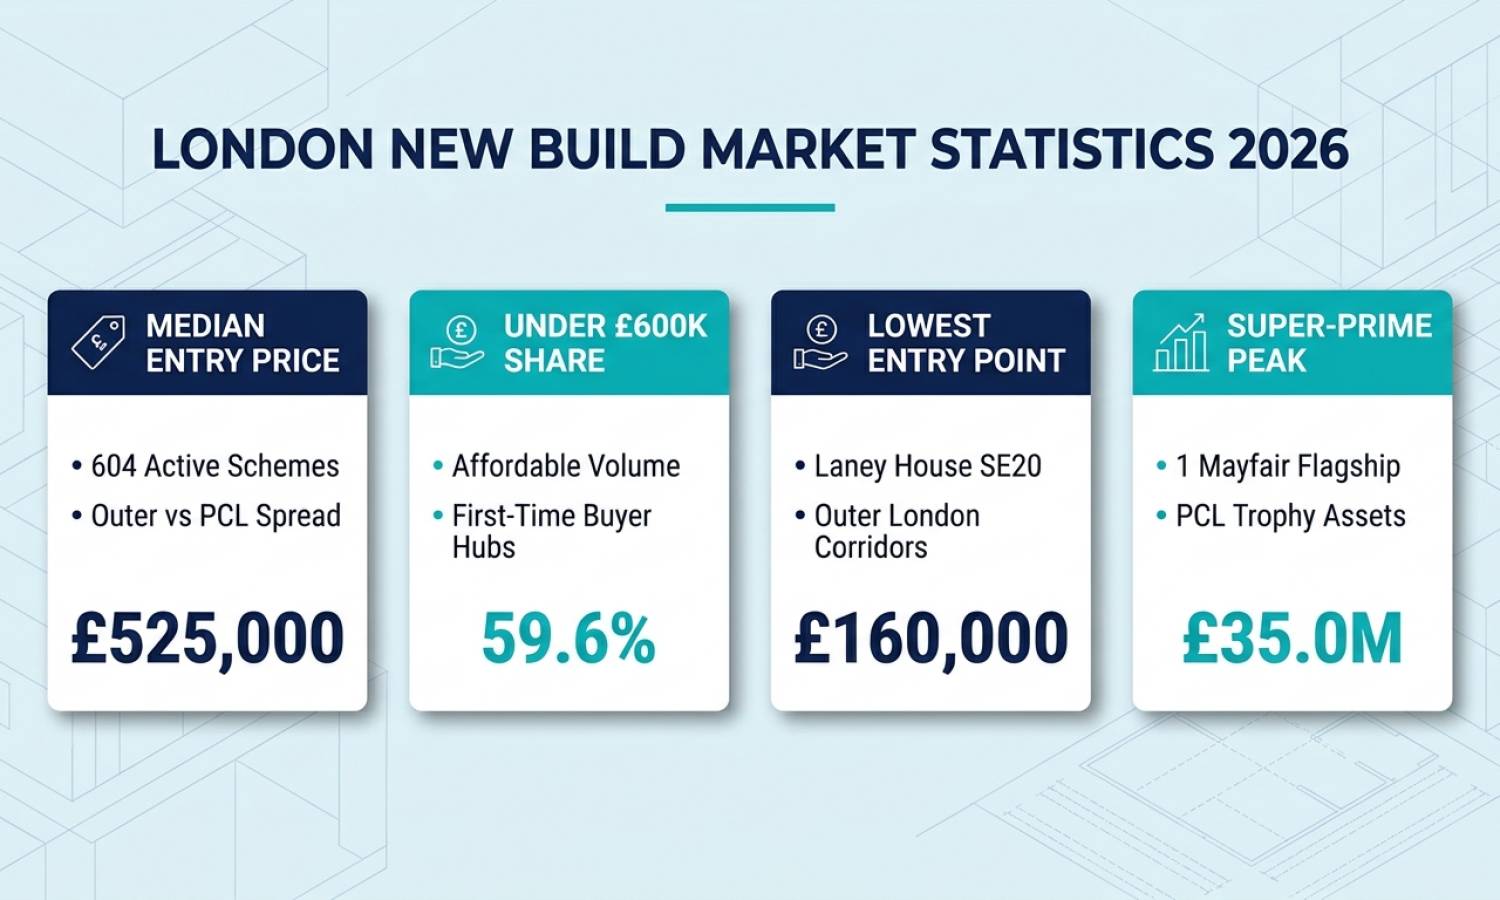
According to comprehensive inventory data from the 1newhomes Research Division tracking 604 active residential developments across Greater London, the overall median entry price for a London new build stands at £525,000. Despite record high land and construction costs, 59.6% of active capital schemes start below £600,000, driven by Outer London regeneration nodes in zones 3 to 5.
This market analysis provides home seekers, institutional analysts, and investors with verified pricing benchmarks drawn directly from active developer stock. The underlying dataset covers developments ranging from entry-level studios at £160,000 to prime central London penthouses at £35,000,000, indexed under open scientific licensing (DOI: 10.5281/zenodo.24156524) via the 1newhomes Open Data Portal.
Executive Market Benchmarks (November 2026)
Evaluating active London inventory reveals a wide gap between mainstream domestic schemes and prime central enclaves. While the mean starting price sits at £1,186,037 due to multi-million pound super-prime residences, the median price of £525,000 reflects where typical residential transactions occur:
| Metric | Recorded Value | Dataset Scope | Market Context |
|---|---|---|---|
| Median Entry Price | £525,000 | 604 active schemes | Typical entry threshold across Greater London boroughs |
| Mean Entry Price | £1,186,037 | 604 active schemes | Elevated by luxury penthouses in Mayfair and Kensington |
| Minimum Starting Price | £160,000 | Laney House, SE20 | Shared ownership and pocket apartment inventory in South East London |
| Maximum Starting Price | £35,000,000 | 1 Mayfair, W1K | Super-prime flagship development by Caudwell |
| Mainstream Supply Share (<£600k) | 59.6% (360 schemes) | Outer zones 3 to 5 | Primary target volume for first-time buyers and domestic movers |
London New Build Pricing Tier Distribution
When categorising new build developments in London by entry price brackets, the largest concentration of inventory falls between £400,000 and £600,000. This segment represents nearly a third of all ongoing construction projects across the capital:
| Price Bracket | Active Developments | Market Share | Core Profile & Locations |
|---|---|---|---|
| Under £400,000 | 165 | 27.3% | Entry-level studios and one-bedroom flats supported by the First Homes Scheme and Shared Ownership. |
| £400,000 to £600,000 | 195 | 32.3% | Young professionals and families targeting Outer London growth hubs like Enfield, Croydon, and Harrow. |
| £600,000 to £1,000,000 | 121 | 20.0% | Inner Zone 2 and Zone 3 apartments, dockside regeneration in Canary Wharf, and prime transport interchanges. |
| £1,000,000 to £2,500,000 | 78 | 12.9% | Upper-tier residences, riverfront luxury developments, and Zone 1 commuter districts. |
| £2,500,000 and Above | 45 | 7.5% | Prime Central London (PCL) flagship developments in Mayfair, Kensington, Chelsea, and Belgravia. |
Most Affordable Entry-Level Developments in Greater London
For buyers focused on capital preservation and manageable mortgage commitments following recent monetary policy adjustments from the Bank of England base rate increase, several Outer London schemes offer verified entry points below £250,000:
| Development | Starting Price | Developer | Location & Postcode | Transport Connections |
|---|---|---|---|---|
| Laney House | £160,000 | NHG Homes | High Street, SE20 | Anerley & Penge West national rail links |
| Addiscombe Grove | £199,999 | Pocket Living | East Croydon, CR0 | 15-minute direct trains to London Bridge |
| Copperhouse Green | £230,000 | Bellway | Dartford border, DA1 | Direct commuter line to London Cannon Street |
| Medford House | £230,000 | McCarthy & Stone | Bexley, DA5 | Bexley rail station with suburban access |
| The Lightworks | £240,000 | Guinness Partnership | Northolt Road, HA2 | South Harrow Piccadilly line tube station |
For more details on entry-level options, explore our curated analysis of the cheapest areas to buy a new build in London under £500,000.
Ultra-Prime Flagship Schemes in Central London
At the opposite end of London residential supply, international capital continues to anchor ultra-prime developments. These projects feature boutique architectural finishes, private wellness clubs, and hotel-style services that drive pricing far above standard residential stock:
| Development | Starting Price | Developer | Borough & Postcode | Distinctive Asset Profile |
|---|---|---|---|---|
| 1 Mayfair | £35,000,000 | Caudwell | Westminster (Mayfair, W1K) | Bespoke residences designed by Robert A.M. Stern Architects |
| 32-34 Avenue Road | £30,000,000 | Prime Developers | Camden (St John's Wood, NW8) | Private gated villas with private subterranean leisure facilities |
| The Glebe | £27,700,000 | Orion Land & Leisure | Kensington & Chelsea (Chelsea, SW3) | Discrete prime apartment enclave designed by Foster + Partners |
| Wilton Crescent | £25,000,000 | Leconfield Property | Westminster (Belgravia, SW1X) | Restored Portland stone heritage architecture with private mews |
| 26 Upper Brook Street | £25,000,000 | Westminster Estates | Westminster (Mayfair, W1K) | Grand architectural townhouse conversion into luxury suites |
Geographic Stratification: Outer Regeneration vs Inner London
A central finding from the 604-scheme dataset is that developers concentrate high-density construction in regeneration zones that connect directly to rapid transit. For buyers evaluating new build flats in London, geographic choices determine both entry costs and potential rental returns:
- Outer London Transit Hubs: Boroughs along the Elizabeth line and national rail corridors, including Croydon, Bexley, and North London developments, account for the vast majority of units priced below £500,000.
- Yield Advantages for Landlords: In contrast to Prime Central London yields of 2.8% to 3.5%, outer suburban developments produce net yields between 6.0% and 7.2%, as documented in our detailed report on the highest rental yield postcodes in London.
- Construction Cost Floors: Because modern new builds must adhere to strict Future Homes Standards and EPC B or A ratings, baseline building costs prevent developers from dropping prices below approximately £450 per square foot in Greater London, establishing a firm price floor.
Data Methodology and Academic Citation
This report draws from verified primary listing inventory monitored by the 1newhomes market intelligence team. The data records 604 distinct development developments, excluding second-hand re-sales to ensure accurate reflection of developer pricing structures.
To support open housing research, urban planning analysis, and academic study, the underlying dataset is catalogued under open data protocols:
- Research Repository Portal: 1newhomes Open Data Portal
- Permanent Archive Identifier: CERN Zenodo DOI: 10.5281/zenodo.24156524
- Academic Citation: 1newhomes Research (2026). "London New Build Market Statistics 2026: Pricing, Boroughs & Supply Report". 1newhomes.com. DOI: 10.5281/zenodo.24156524.
Frequently Asked Questions
FAQ
Across 604 active London new build developments, the median entry price is £525,000. The mean entry price is higher at £1,186,037, reflecting multi-million pound super-prime residences in central London boroughs.
Approximately 59.6% of all active new build developments in Greater London start below £600,000. This includes 165 schemes priced under £400,000 and 195 schemes priced between £400,000 and £600,000, primarily located in outer boroughs.
Outer London boroughs including Bromley (SE20), Croydon (CR0), Bexley (DA5), and Harrow (HA2) offer the lowest new build entry prices, with starting values ranging from £160,000 to £240,000.
The complete underlying dataset tracking 604 active London residential developments is accessible through the 1newhomes Open Data Portal under permanent DOI 10.5281/zenodo.24156524 for academic and market research.


